
Share On:
Your First Home: Help To Buy 2.0
With the news that the government are bringing in what is effectively a Help To Buy mark 2 in, we thought we would take a look and work out how it is likely to effect the UK property market. Whilst a lot of detail is due to come out in the new budget at the end of October we feel that this can only really be a positive thing for the market.
Spoiler alert – demand up, supply down, prices likely to rise.
How will it affect the UK property market?
Immediately after the announcement, share prices in England’s major plc housebuilders surged. Persimmon closed 14% higher, Barratt Redrow, 11.7% higher, Taylor Wimpey 11.3% higher, Crest Nicholson 11% higher and Vistry 10.7% higher.
There’s little doubt that this scheme will help thousands of first time buyers, struggling in the face of higher lending rates, to get on the ladder. Help To Buy enabled 328,000 first time buyers to purchase their first home, but it also drove prices up in the new build sector. Thus, we expect to see a huge boost to the new build sector in terms of transaction volumes and prices. No wonder share prices rallied.
For overseas property investors, the current buyer’s market now presents a window – a strong opportunity to buy at a discounted rate before the prices begin to rise – which they will. If it is as successful as the last scheme, 328,000 new build buyers potentially entering a market where new build homes are at their lowest level of delivery since World War II, will send prices up sharpish. Again, no wonder those share prices surged.
A recent study attributed an 8% rise in new build prices in the first year of Help To Buy. Which is why buying now presents a smart opportunity to capitalise on the future market appreciation. Economists watching for a South East recovery tend to look at first-time buyer mortgage approval data as an early signal, rather than waiting for the price indices to move, since approvals tend to turn before completions and prices do. Therefore, Your First Home is exactly the boon needed to get prices moving again in the South East, an area which is underperforming the English regions.
Why are First Time Buyers such a bellwether for the UK market?
First-time buyers sit at the bottom of the property chain, and that position gives them outsized influence on the rest of the market.
They’re the entry point for chains
Most UK transactions happen in chains: A buys from B, who buys from C and so on…A first-time buyer is usually the only person in that chain who isn’t simultaneously selling. If first-time buyers can’t or won’t transact, the chain above them often can’t complete either. So their activity level is a leading indicator for transaction volumes across the whole market, not just the bottom rung.
They set the pace of new demand entering the market
Existing owners moving house are recycling demand that already exists. First-time buyers represent genuinely new demand entering the system. If that inflow slows, the whole market has fewer net transactions to work with, even if existing owners still want to move.
They’re a large share of transactions
First-time buyers regularly account for roughly half of all mortgaged property purchases in the UK in a given year. That’s a big enough share that their confidence and ability to buy meaningfully moves overall volume statistics.
They’re closely tied to sentiment and confidence
Because first-time buyers are making a discretionary, high-commitment decision without the cushion of existing housing equity, their willingness to buy reflects consumer confidence, job security perceptions and affordability sentiment more directly than an existing owner’s decision to trade up or down. A pullback in first-time buyer activity is often read as an early sign that confidence is weakening, before it shows up in headline price indices.
Talk to Us Today
No matter where you are in the world, talk to us today. You can browse our current UK developments in London, Birmingham, Manchester and Liverpool.
What is Your First Home?
Your First Home is the new UK government scheme designed to help first time buyers looking for a new build home or apartment in England (not Scotland, Wales or Northern Ireland).
Buyers can get an initially interest free government-backed equity loan for 20% of the property’s purchase price with a 2.5% minimum deposit – a fraction of the usual 5-10% required. Mortgages will be taken out at most, at 77.5% of the property’s value, a moderate. LTV in today’s market, particularly for first time buyers.
The scheme has a number of safeguards and caps to stop it being hijacked or abused by those with big salaries looking for more favourable lending conditions, including: A household income cap for applicants (varied by region), deposit caps to limit how much you can put down and local property caps to limit how much you can spend on a new build property, depending on the local area where you live.
Full eligibility details will be released in the budget on 28th October and the scheme will be ready to accept registrations of interest by the end of this year. Reuters were one of the few news outlets to report the initial interest free period on the 20% equity loan as five years.
Qualifying properties will be capped at £600,000 – although this cap will depend where you live – and will only be available from developers signed up to the scheme, therefore not all new build homes will be applicable.
Who can apply?
First-time buyers in England only
Buying a new-build property, from a developer signed up to the scheme
Subject to a regional household income cap (not yet specified)
Subject to a property price cap of up to £600,000 (likely lower in cheaper regions, similar to how Help to Buy varied regional caps)
That’s all we know so far. Whether the scheme will have age limits, be restricted to owner-occupiers and if homeowners with no current property (e.g. after divorce) count as ‘first-time buyers’ aren't yet confirmed. Exact eligibility criteria will be detailed on 28th October.
Get expert guidance on buying international property
FEATURED PROPERTY
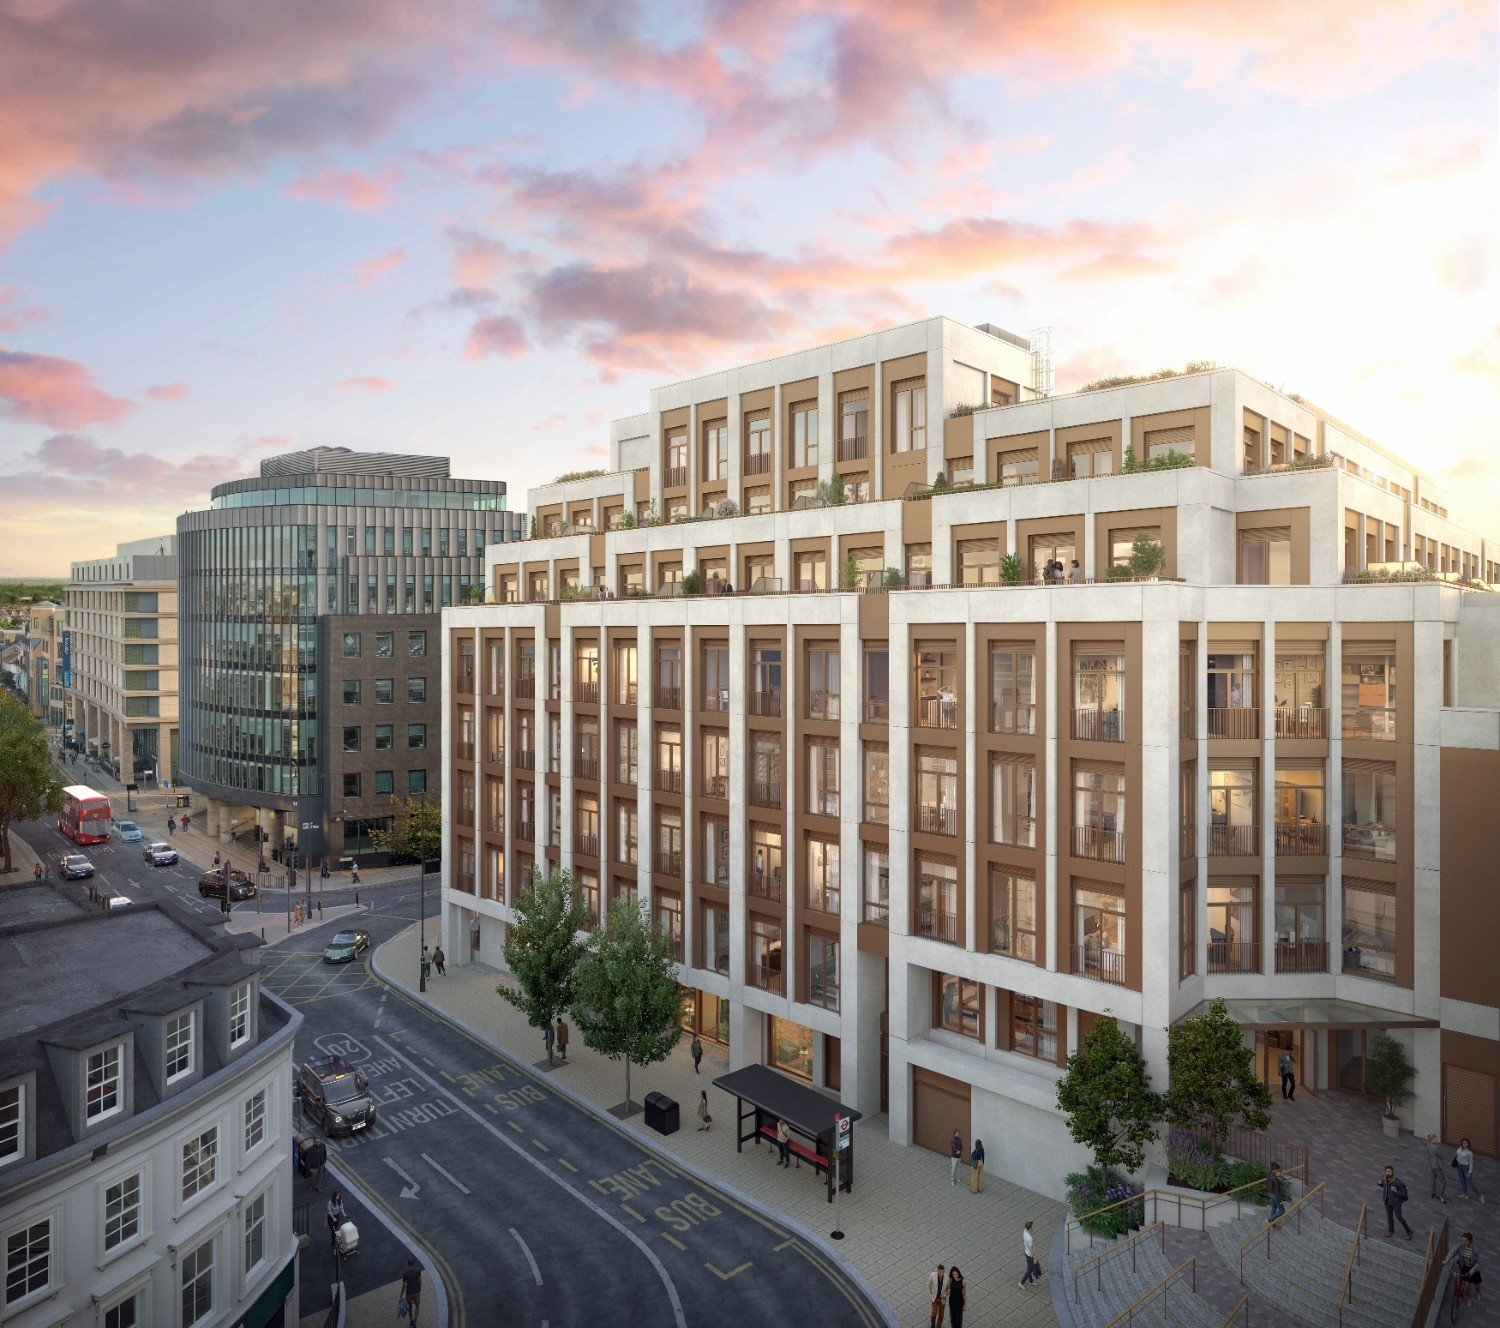
wimbledon bridge house

From £487,500
10% Downpayment
About the author

richard bradstock
Founder & Managing Director
RPA’s founder, Richard has worked in residential development investment for 20 years and oversees the general running of the business ensuring the RPA Group retains true to its founding principles. Over his career Richard has built an incredible network of international property investors and like-minded industry professionals.
READ OUR PREVIOUS BLOG POST